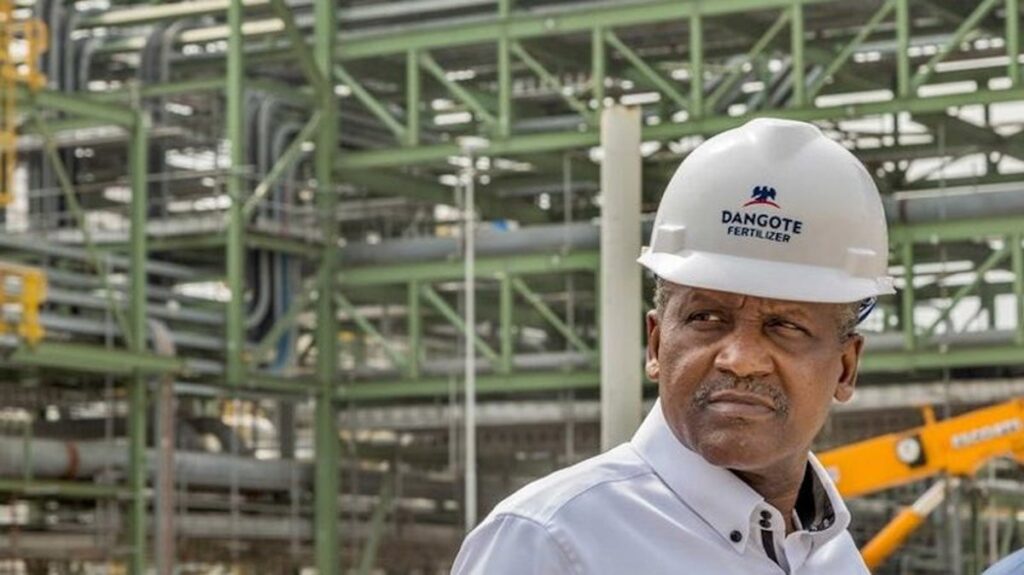
Dangote Petroleum Refinery and Petrochemicals’ initial public offering (IPO) enters its final week with investors weighing one of Nigeria’s largest-ever equity deals against the capital demands of a planned refinery expansion that could double processing capacity by 2029.
The offer closes in a weeks’ time on Oct. 13, with Dangote selling 4.1 billion shares at ₦525 each.
It seeks to raise ₦2.15 trillion before costs, giving the company an indicative post-listing equity value of ₦65.22 trillion. After estimated expenses of ₦41.49 billion, the refinery expects net proceeds of approximately ₦2.11 trillion for its phased expansion program.
The company can accept additional subscriptions of up to 30% of the offer size, subject to Securities and Exchange Commission approval. That creates room for as many as 1.23 billion additional shares, or approximately ₦645.75 billion at the offer price, if demand proves sufficiently strong and the company exercises the option.
The IPO is not underwritten, however, meaning the company has not received a guarantee from banks that all shares will be sold. Why Oversubscription Is Plausible
Several features make an oversubscription possible, although it cannot be assumed before the book closes and allocations are approved.
The deal is being distributed through a broad set of Nigerian banks, brokers and digital investment platforms, including NGX Invest, Bamboo, Flutterwave, Moniepoint, PiggyVest, Cowrywise, MTN MoMo, Paga, Remita, Airtel Smartcash and other financial intermediaries.
The prospectus also provides an African Distribution Channel through Ecobank Transactional Incorporated and SBG Securities, broadening access for eligible investors across the continent.
The deal is designed to reach beyond Nigeria’s domestic investor base. The prospectus defines eligible African investors as residents or entities in African jurisdictions outside Nigeria, subject to local law and the relevant distribution-channel process. Retail investors include both resident and non-resident Nigerians, provided they meet the offer requirements.
That structure offers a formal route for African and diaspora demand, but the strength of those flows will only become clear after the offer closes.
MoneyCentral however gathered that demand from the diaspora and Africa continent has been strong.
The investment case for Dangote Refinery rests on a sharp operational and financial inflection. Dangote began commercial refinery operations in January 2024, reached stable full-capacity operations across major processing units from March 2026 and achieved performance-testing throughput of up to 700,000 barrels a day in June.
Revenue in the first half exceeded the ₦18.77 trillion reported for all of 2025, while profit after tax was more than three times the full-year 2025 result of ₦724.2 billion. The improvement reflects a larger operational base, stronger product volumes and fixed-cost absorption after the refinery’s commissioning phase.
PMS accounted for 42.5% of H1 revenue, followed by diesel at 25.2% and jet fuel at 23.7%. The product mix gives investors exposure to the domestic transport-fuels market, but also to export opportunities across Africa and global markets.
The IPO proceeds will finance only part of the planned $14.3 billion expansion program. The company intends to add about 700,000 bpd of capacity, taking total refining capacity from 700,000 bpd to roughly 1.4 million bpd by 2029. It also plans to deepen petrochemical integration and related infrastructure.
Renaissance Capital Africa estimates Dangote Refinery’s post-IPO equity value at $57.11 billion to $65.44 billion, equivalent to $0.46 to $0.53 a share, or about ₦608.20 to ₦696.94 a share on a post-offer, enlarged-share-count basis, positioning the high end fair value some 32% above the SEC-approved public offer price of ₦525.00 per share.
MoneyCentral’s earlier research report set a ₦1,020 12-month target price, based on an aggressive growth valuation framework. At the ₦525 IPO price, the MoneyCentral target implies a roughly 94.3% upside.
Securities firm Chapel Hill Denham formally initiated equity research coverage on Dangote Petroleum Refinery & Petrochemicals FZE (DPRP), placing the company’s current fair market equity value at $62.53 billion (₦82.62 trillion), equivalent to about ₦667 per share. The offer closes Oct. 13, but investors should not expect trading immediately thereafter.
In practical terms, trading is expected only after SEC approval of the basis of allotment and settlement into successful investors’ CSCS accounts.